Does Insurance Cover Water Damage at Home?
A supply line breaks behind the washing machine. By the time you find it, water has reached the baseboards, flooring, and the room below. The first question is usually urgent: does insurance cover water damage? Often, yes – but the cause of the water matters as much as the damage itself.
Most homeowners, renters, and commercial property policies may cover sudden, accidental water damage. They usually do not cover every source of water or damage that developed slowly over time. The right response is to stop the source if it is safe, document what happened, notify your insurer, and begin professional mitigation quickly. Waiting can turn a manageable water loss into damaged materials, mold growth, and a more complicated claim.
Does Insurance Cover Water Damage From a Burst Pipe?
A standard homeowners policy commonly covers damage caused by a sudden and accidental plumbing failure. That can include a burst pipe, a failed water heater, an overflowing appliance, or a broken supply line. If water damages drywall, cabinets, flooring, furniture, or other covered belongings, the policy may help pay for drying, removal, repairs, and replacement, subject to your deductible and policy limits.
There is an important distinction: the policy may cover the water damage caused by the failed item without covering the cost to replace the failed item itself. For example, an insurer may pay to dry the kitchen and repair water-damaged flooring after a dishwasher supply line fails, while leaving the cost of a new supply line or dishwasher to the homeowner.
Coverage also depends on whether the loss was truly sudden. A pipe that breaks overnight is different from a pipe that has been dripping inside a wall for months. The first is more likely to be covered. The second may be treated as a maintenance issue, especially if there were visible warning signs such as staining, warped flooring, a musty odor, or a steadily rising water bill.
Water Damage That Insurance May Cover
Every policy has its own language, endorsements, limits, and exclusions, but sudden accidental events are often the strongest basis for a claim. Common examples include a washing machine hose that ruptures, an upstairs toilet that overflows unexpectedly, a water heater that fails, or a pipe that freezes and bursts during a cold snap.
Roof-related water damage can also be covered when a covered event creates the opening. If a storm damages the roof and rain enters immediately afterward, the resulting interior water damage may be covered. In Texas, this can be especially relevant after severe wind, hail, or heavy rain. The condition of the roof and the specific cause of the opening still matter.
Water damage from fire suppression systems may also qualify when a sprinkler system discharges because of a covered event or accidental activation. Commercial property policies can have additional conditions, including business property, equipment, inventory, and business-income coverage. Property managers and business owners should review their specific forms rather than relying on residential coverage rules.
What Water Damage Is Commonly Excluded?
The source of the water is where many claims change direction. A policy that covers a burst indoor pipe may exclude water that enters from outside during a flood. It may also limit or exclude damage tied to poor maintenance, repeated leakage, or backup from a drain or sewer line.
Flood damage is typically not covered under a standard homeowners policy. Flood insurance is generally a separate policy, and it may apply when water rises or flows onto normally dry land from outside. Heavy rainfall, overflowing creeks, storm surge, and drainage overflow can all create situations where flood coverage, not a standard property policy, is needed.
Sewer and drain backups are another frequent surprise. Some policies offer limited coverage only when the owner has purchased a water backup endorsement. Without that endorsement, cleanup from a backed-up drain, sewer, or sump pump can become an out-of-pocket expense. Because wastewater can carry contaminants, this is not a situation to handle casually.
Insurance companies may also deny or limit claims involving neglect or wear and tear. Examples can include a long-term roof leak, deteriorated caulking around a shower, an appliance connection that was visibly corroded, or mold caused by unresolved moisture. The policy is designed for unexpected losses, not routine upkeep that was deferred.
What to Do Immediately After Water Damage
Your first job is safety. Do not enter standing water if electricity may be involved, and do not touch wet electrical equipment. If water is coming from a plumbing failure, turn off the water supply only if you can do so safely. If the source is wastewater, floodwater, or another contaminated source, keep people and pets away from the affected area.
Next, take clear photos and video before moving items whenever possible. Capture the source of the water, affected rooms, damaged belongings, and any visible damage to walls, ceilings, floors, or contents. Save receipts for reasonable emergency expenses, such as temporary lodging if the home is unlivable or materials used to protect unaffected property. Your insurer can explain its documentation requirements, but detailed records help establish what happened and when.
Then report the loss promptly. Ask your insurance carrier or agent whether a claim should be opened, what deductible applies, whether a field adjuster will inspect the property, and whether emergency mitigation can begin right away. You do not need to leave water sitting in the structure while waiting for every claim decision. In fact, policies usually require you to take reasonable steps to prevent additional damage.
Professional water mitigation focuses on more than extracting visible water. Moisture can move beneath flooring, behind baseboards, into insulation, and inside wall cavities. A qualified restoration team uses moisture detection, controlled drying equipment, documentation, and monitoring to identify affected materials and reduce the risk of secondary damage. If materials cannot be dried safely, they may need to be removed before repairs and reconstruction begin.
How to Avoid Mistakes That Can Complicate a Claim
Do not throw away damaged materials before they are documented unless they create an immediate health or safety concern. Take photographs, keep samples if appropriate, and ask your adjuster or restoration provider how to handle disposal. At the same time, do not keep wet carpet, drywall, insulation, or contents in place simply because you are worried about evidence. Mitigation documentation can preserve the record while protecting the property.
Avoid making permanent repairs before the damage is documented and the insurer has had an opportunity to review the loss, unless emergency repairs are necessary to stop further damage. Temporary steps such as tarping a damaged roof area, stopping a leak, or extracting standing water are generally sensible. Keep receipts and written notes of what was done.
Be accurate when describing the cause. “Water damage” is not a cause by itself. Was it a supply line failure, appliance overflow, storm-related roof opening, sewage backup, or rising floodwater? A clear timeline helps the insurer evaluate coverage and helps the restoration team create the right scope of work.
When Water Damage Becomes a Restoration Project
A small, clean-water overflow caught quickly may need limited extraction and drying. A loss that reaches multiple rooms, soaks building materials, or involves sewage or floodwater needs a more controlled response. The longer materials stay wet, the more likely they are to swell, delaminate, stain, or support microbial growth.
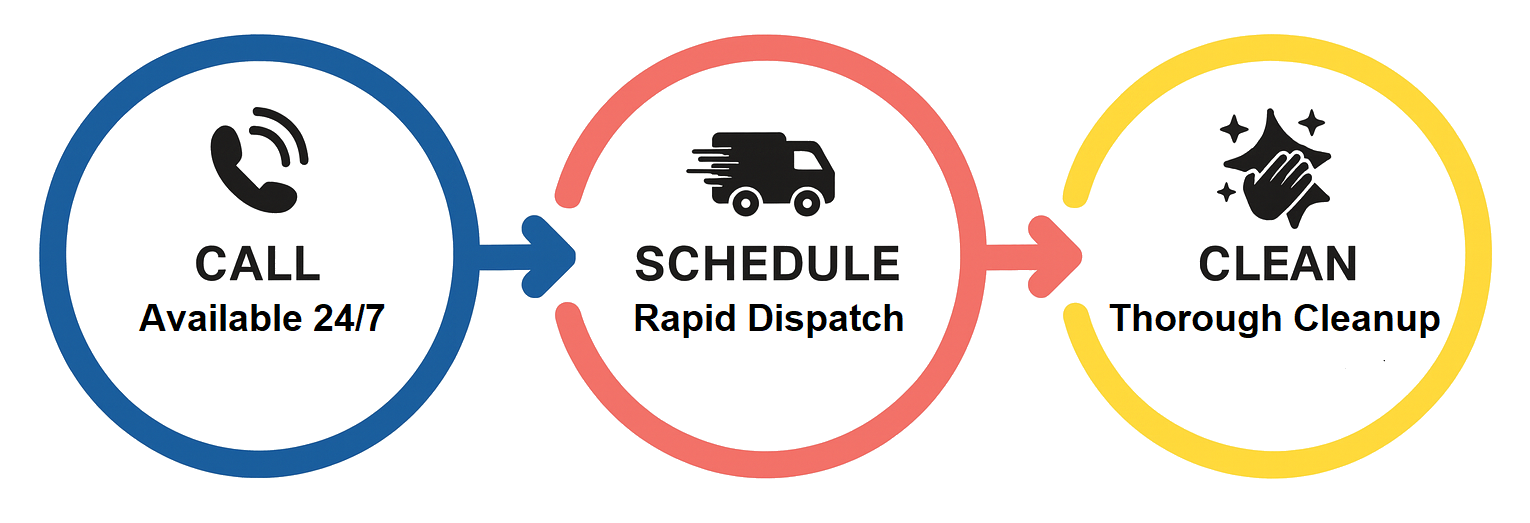
That is why the best question is not only whether the policy will pay. It is also how quickly the property can be stabilized. In an emergency, Renew Cleaning & Restoration can handle inspection, water removal, drying, cleanup, mitigation, repairs, and reconstruction through one accountable team. For Texas homeowners, businesses, and property managers, that means less time coordinating vendors while the damage spreads.
Insurance coverage is never automatic, and no restoration company can promise what an insurer will approve. But fast documentation, proper mitigation, and a clear record of the cause give you a stronger starting point. Protect the property first, keep the facts organized, and get qualified help before hidden moisture turns one bad day into a longer recovery.